Small Business Health Insurance in ColoradoBetter Benefits for Your Team. Smarter Solutions for Your Business.
Explore traditional group health insurance, ICHRA alternatives, and supplemental employee benefits with personalized guidance designed around your workforce and budget.
Group plans and ICHRA options, compared side by side.
Healthcare industry experience
15+ Years
Business & healthcare credentials
MBA · MHA
Colorado insurance license
#940714
For your consultation
No Cost
Benefits solutions
Employee Benefits Solutions for Colorado Small Businesses
Four ways we can approach benefits for your team. Many businesses combine more than one.
01
Traditional Small-Group Insurance
A group health plan your business sponsors, with plan options you choose and a share of premiums you contribute. A familiar approach that many employees recognize.
Often a fit for: Teams that want one shared plan and a traditional benefits package
02
ICHRA (Individual Coverage HRA)
Instead of a group plan, you set a monthly allowance and reimburse employees for individual health insurance they choose — with allowances that can vary by employee class.
Often a fit for: Employers who want a defined budget and more employee choice
03
Supplemental & Ancillary Benefits
Dental, vision, life, and other supplemental coverage that can round out your benefits package — whether you offer a group plan, an ICHRA, or are just getting started.
Often a fit for: Businesses building a more complete, competitive package
04
Annual Renewal Strategy
A structured review of your renewal before you sign — what changed, what your options are, and whether a different plan design or approach is worth considering.
Often a fit for: Groups with an upcoming renewal or a recent rate increase
Compare approaches
Small Group Health Insurance vs. ICHRA
Choose a topic to see how a traditional group plan and an Individual Coverage HRA compare. Neither is right for every business — it depends on your team, budget, and goals.
Employer Cost Structure
Small-Group Plan
The carrier sets premiums for the group, and you typically pay a share of each employee's premium. Costs can change at each annual renewal, and carriers often require a minimum employer contribution.
ICHRA
You choose a fixed monthly allowance — which can differ by employee class — and reimburse qualifying individual premiums up to that amount. Your contribution is set by you; employees' premiums vary by plan, age, and location.
Employee Choice
Small-Group Plan
Employees choose from the plan options you select — often one or a few plans from a single carrier and network.
ICHRA
Employees shop for their own individual plan, which may offer more choice of carriers, networks, and price points, depending on what's available where they live.
Administration
Small-Group Plan
One group policy with consolidated billing. You manage enrollment, carrier participation requirements, and the annual renewal.
ICHRA
Requires a formal written arrangement, verifying that employees have individual coverage, and processing reimbursements — often handled with help from an ICHRA administrator.
Compliance Considerations
Small-Group Plan
Carriers set participation and contribution rules, and group plans carry federal and state requirements such as required notices and continuation-of-coverage rules.
ICHRA
ICHRAs follow specific federal rules — including how employee classes are defined, written notices before the plan year, and affordability rules that affect Marketplace premium tax credits. Plan your setup with a qualified administrator and tax advisor.
A group plan may suit you if…
You want one shared plan for the whole team
Your employees value a familiar group plan experience
Most of your team lives and works in the same area
An ICHRA may suit you if…
You want a defined, predictable benefits budget
Your team has varied needs, ages, or locations
You'd like employees to choose their own plan
This comparison is general information, not tax or legal advice. Rules and costs depend on your business and the plans available. Consult a qualified tax advisor or benefits administrator about tax treatment and compliance.
Is a review right for you?
Which Businesses May Benefit From a Benefits Review?
Whether you have three employees or fifty, a review can clarify where you stand and what's worth considering next.
Understand your options and what a realistic budget looks like before you commit.
Facing a renewal increase
Get a second opinion on your renewal and see what alternatives may be available.
Growing your team
Make sure your benefits strategy keeps pace as you hire and compete for talent.
Employees in different locations
Remote or spread-out teams may find an ICHRA worth evaluating alongside a group plan.
Mixed full-time & part-time staff
Explore how different benefit approaches can work for different employee groups.
Practices, shops & family businesses
Medical and dental offices, restaurants, contractors, nonprofits, and family-owned companies.
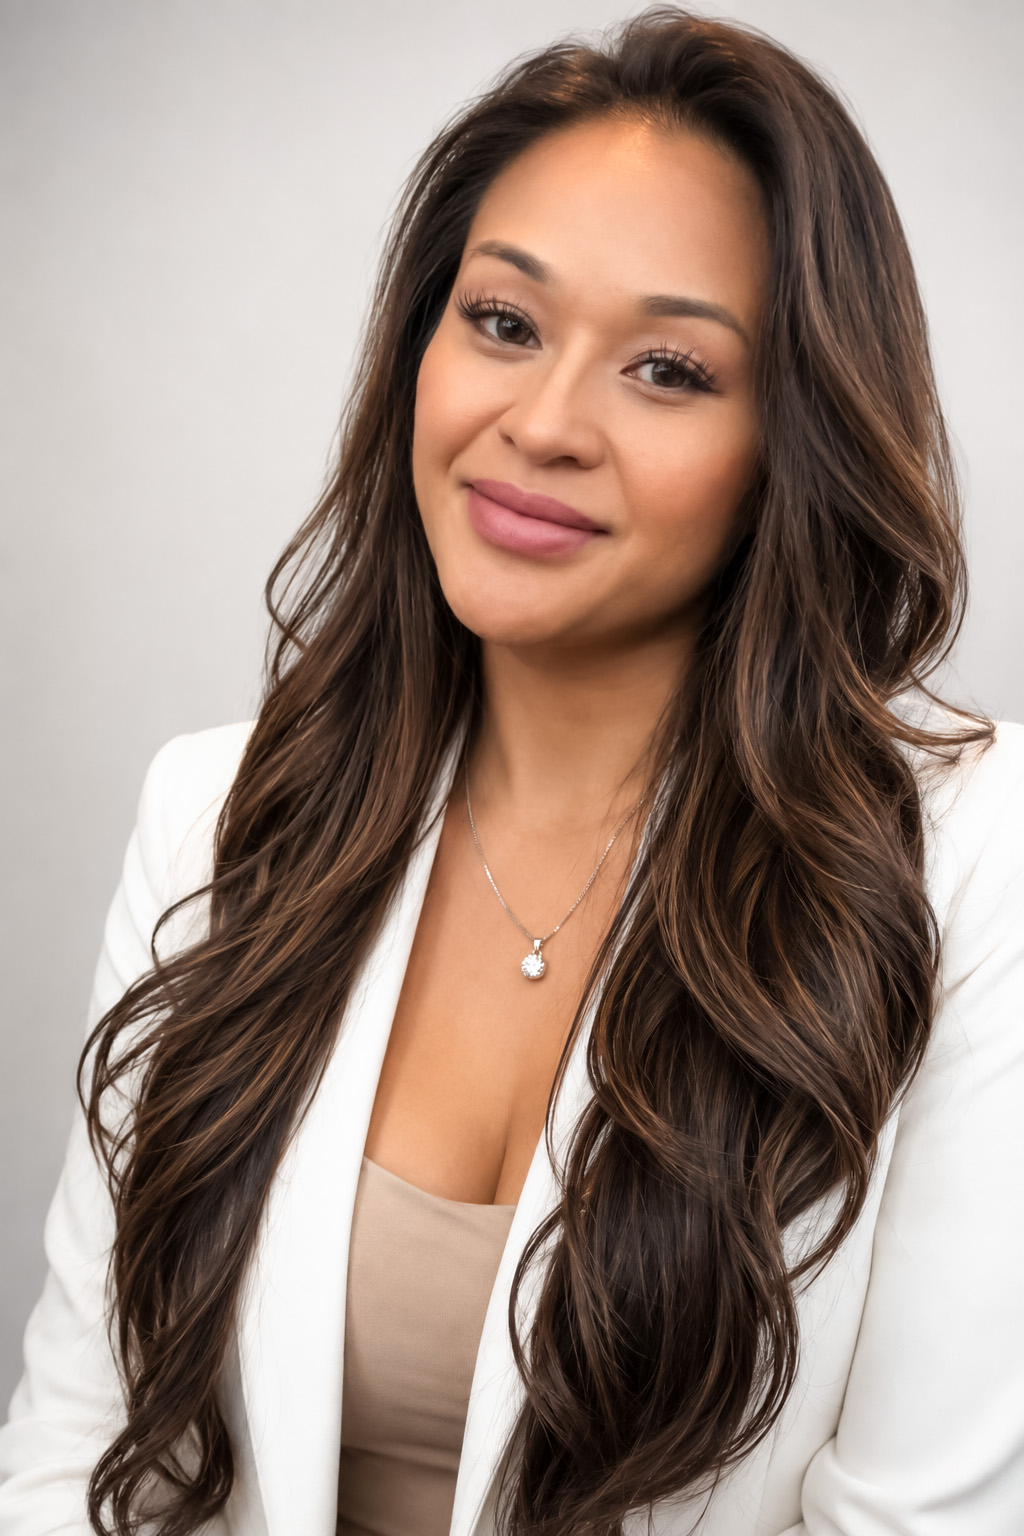
Mai Huynh, MBA, MHA
Independent Agent · HealthMarkets
Your benefits advisor
Healthcare Expertise Meets Business Strategy
I spent more than 15 years inside hospitals, physician practices, and health plans, and I hold both an MBA and an MHA. That combination helps me explain how health coverage actually works — and weigh it against your budget, your team, and your goals as a business owner.
15+ Years
Inside hospitals, physician practices, and health plans
MBA
Business strategy, budgeting, and cost analysis
MHA
Healthcare administration and operations
Independent
Options from multiple insurance companies through HealthMarkets
What I do — and don't do: I'm a licensed health and life insurance agent (Colorado #940714) who helps you understand and compare coverage options. I'm not a tax advisor, attorney, or benefits administrator. For tax treatment, legal compliance, and ICHRA administration, I'll recommend you work with qualified professionals.
HealthMarkets Insurance Agency offers the opportunity to enroll in either Qualified Health Plans (QHPs) through the Health Insurance Marketplace or off-Marketplace coverage. Please visit HealthCare.gov for information on the benefits of enrolling in a QHP. Off-Marketplace coverage is not eligible for the cost savings offered through the Marketplace.
Let's Build a Benefits Strategy That Fits Your Business
A free, no-obligation conversation about your team, your budget, and your options — group plans, ICHRA, and supplemental benefits.