1. Family Protection
Family & Financial Protection
Life insurance may help loved ones replace lost income, maintain mortgage payments, manage debts, and fund future education or living expenses.
Life insurance is more than a death benefit. It's a tool for protecting what matters and planning for what comes next.
Whether you're protecting your family, building a business, or preparing for retirement, life insurance can play an important role in your broader financial strategy.
From affordable term coverage to permanent life insurance with potential cash value benefits, I'll help you explore options that align with your financial goals, responsibilities, and budget.
People use life insurance for different reasons. Here are four of the most common — and how coverage may fit into each.
1. Family Protection
Life insurance may help loved ones replace lost income, maintain mortgage payments, manage debts, and fund future education or living expenses.
2. Retirement Planning Considerations
Certain permanent life insurance policies build cash value that may be accessed during your lifetime through withdrawals or policy loans. These features may complement retirement savings strategies.
Loans and withdrawals can reduce policy values and death benefits, create tax consequences, or cause a policy to lapse.
3. Business Protection
Life insurance can help businesses prepare for the loss of an owner or key employee, fund certain buy-sell arrangements, and support business continuity.
4. Legacy Planning
Life insurance death benefits may provide beneficiaries with financial resources and can be incorporated into broader estate planning strategies.
Subject to applicable tax and legal considerations.
Start with the people and goals that matter to you. Select one or more to see how life insurance may help — before we ever talk about specific policies.
Your protection picture
Choose who or what matters to you, and I'll show how life insurance may help.
Tap each type to see how long it lasts, how premiums work, whether it builds cash value, and the trade-offs to know.
Affordable protection for a set number of years.
Often considered for
Things to know
Indexed universal life is a type of universal life where cash value interest is linked in part to the performance of a market index, such as the S&P 500. Your money is not invested directly in the market. Growth is limited by caps and participation rates, and while many policies include a floor against index losses, policy charges still apply. Returns are not guaranteed, and illustrations are projections — not promises.
It can, in some cases. Certain permanent policies build cash value that may be accessed through withdrawals or policy loans later in life.
But life insurance is not a replacement for traditional retirement accounts. It should be evaluated alongside them — with a clear view of the costs and risks.
Also planning for retirement income? Ask me about fixed and fixed indexed annuities.
What to evaluate first
Loans and withdrawals can reduce policy values and death benefits, create tax consequences, or cause a policy to lapse.
Your business depends on people. Life insurance can help it stay steady if one of them is suddenly gone.
Helps a business prepare financially for the loss of an owner or employee whose skills are hard to replace.
May help fund an agreement that lets remaining owners buy a deceased owner's share from their family.
Can help cover business debt so loans don't become a burden for partners or family.
Some arrangements use life insurance to reward and retain key employees, where available.
Also looking at employee health benefits? See Small Business Benefits.
Many policies offer optional accelerated benefit riders. If you're diagnosed with a qualifying terminal, chronic, or critical illness, these riders may let you access part of your death benefit early to help with care or living expenses.
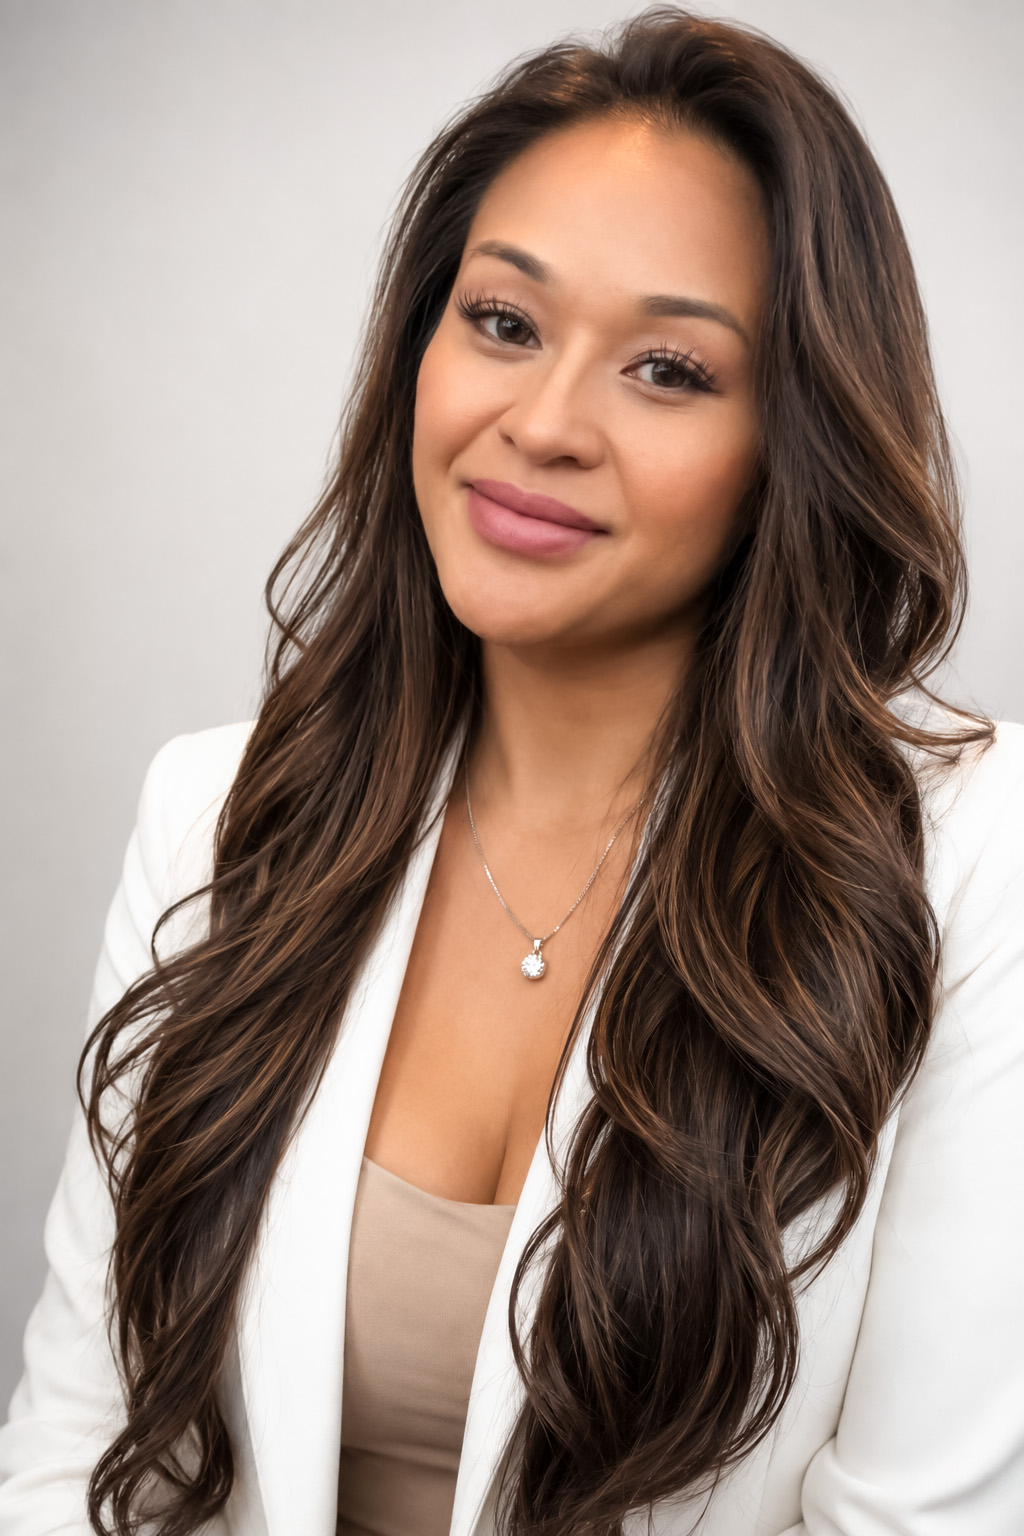
Mai Huynh, MBA, MHA
Independent Health & Life Insurance Agent
As an independent agent with an MBA and MHA, I compare life insurance options so the recommendation is based on your goals and budget — not one company's products.
I'll help you:
No-cost consultations Personalized guidance Ongoing policy reviews
Read Mai's storyWhether you're starting a family, growing a business, or planning for retirement, let's talk through your goals and find coverage that fits your life and budget.
Life insurance is not an investment and does not guarantee retirement income or wealth. Coverage is subject to underwriting, eligibility, and the terms, exclusions, and limitations of each policy. Cash value growth, where available, depends on the policy and is not guaranteed unless stated in the contract. Policy loans and withdrawals reduce cash value and the death benefit and may have tax consequences. This page is educational and is not tax or legal advice — please consult a qualified professional.